ASML Holding (NASDAQ: ASML) reported €11.66 billion in Q3 2026 revenue, a record 57.5% gross margin, and €4.96 billion in net income on October 14. The Dutch semiconductor equipment maker also raised its full-year revenue guidance as AI-driven demand for advanced chipmaking capacity continued to accelerate.
But the earnings story extends beyond headline growth. ASML's installed-base upgrade business exceeded expectations, customers are discussing equipment demand through 2029 and 2030, and management now believes its planned capacity expansion may not fully meet demand.
Meanwhile, the
ASMLUSDT perpetual contract on MEXC showed a displayed change of
−1.73% in an October 14 trading snapshot, illustrating how overnight derivatives pricing can diverge from the fundamental picture.
Key Takeaways
Q3 revenue reached €11.66 billion, up approximately 25% from Q2, while gross margin improved to 57.5%, above ASML's previous guidance.
Installed Base Management revenue reached €3.29 billion, approximately €400 million above management's earlier forecast, driven by productivity upgrades.
Net income totaled €4.96 billion, including approximately €500 million from the revaluation of ASML's Mistral AI investment.
ASML raised its 2026 revenue outlook to €44 billion–€45 billion, from €43 billion–€45 billion previously.
Customers are discussing equipment needs for 2029 and 2030, prompting ASML to consider additional capacity beyond its existing expansion plans.
MEXC ASMLUSDT trading reflected overnight volatility, with contract prices distinct from Nasdaq-listed ASML shares.
ASML Q3 2026 Earnings Results: Revenue, Margin and Profit
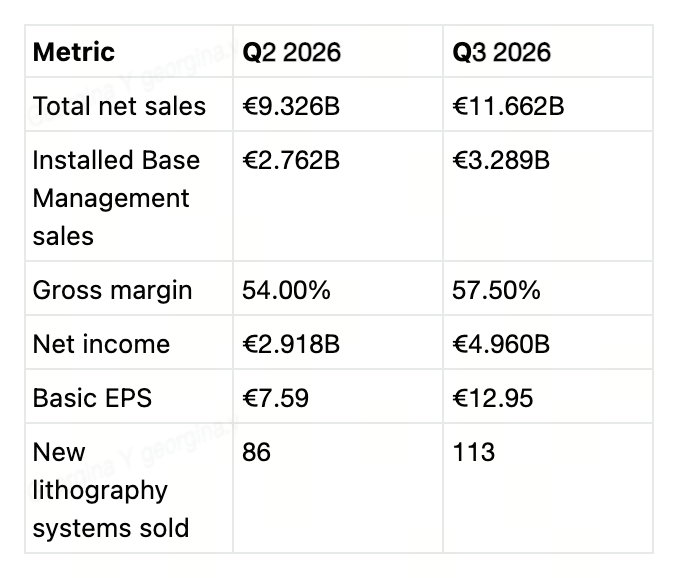
Revenue increased approximately 25% quarter over quarter, while Installed Base Management sales rose about 19%.
ASML's 57.5% gross margin also exceeded its previous Q3 guidance of 55%–57%.
The profit figure requires additional context. CFO Roger Dassen explained that approximately €500 million of quarterly net income came from revaluing the company's investment in French artificial intelligence company Mistral AI.
That contribution should be distinguished from recurring profitability generated by semiconductor equipment sales and services.
The stronger operating performance was nevertheless supported by higher equipment volumes, favorable product mix and customer demand for productivity upgrades.
Why Did ASML's Gross Margin Exceed Guidance?
The most significant operating surprise came from ASML's Installed Base Management business.
The segment generated €3.29 billion in quarterly revenue, approximately €400 million above management's previous expectation.
Rather than waiting for newly manufactured lithography systems, chipmakers are upgrading machines already installed in their factories to increase production capacity.
Higher equipment sales volumes, improving fixed-cost absorption.
A favorable revenue mix involving EUV and immersion lithography systems.
Stronger installed-base revenue, particularly equipment productivity upgrades.
The third factor is especially important because it provides ASML with another way to benefit from semiconductor capacity expansion.
ASML also confirmed that negotiations on higher value-based pricing had been completed with key customers. Management expects part of the benefit to emerge in 2027, with the full effect becoming visible in 2028 and beyond.
Why Did ASML Raise Its 2026 Revenue Guidance?
ASML increased the lower end of its 2026 revenue forecast by €1 billion, reflecting stronger business momentum and higher expectations for the remainder of the year.
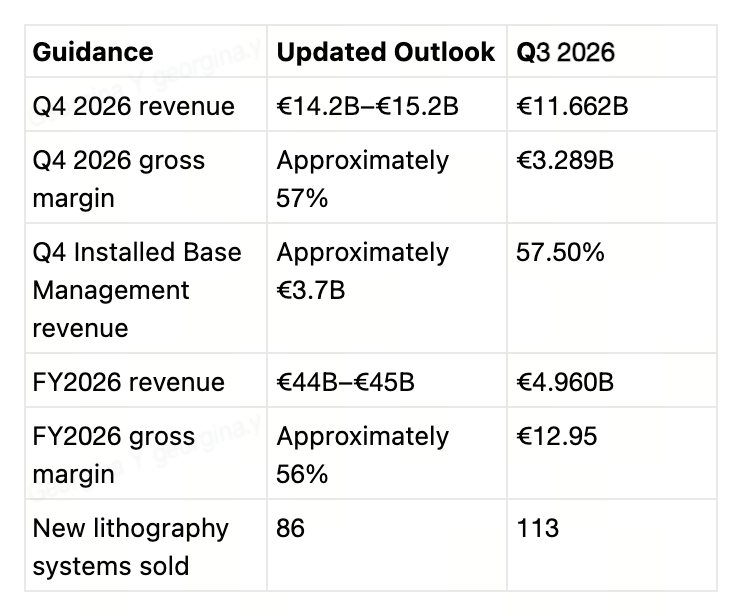
The company previously forecast full-year revenue of €43 billion–€45 billion and a gross margin of 54%–56%.
Management also expects EUV revenue to grow by more than 45% in 2026, non-EUV revenue by approximately 20%, and Installed Base Management revenue by approximately 50%.
These expectations reflect strong demand for both new lithography equipment and upgrades to existing systems.
However, higher demand does not immediately translate into revenue. Equipment manufacturing, delivery, installation and accounting recognition all affect the timing of reported sales.
Why Is ASML Planning More Capacity for 2028?
ASML's capacity outlook may be the most important longer-term development in the Q3 report.
CEO Christophe Fouquet said customers are increasing their equipment demand forecasts as AI infrastructure investment extends beyond the near term.
According to management, customers generally expect their own semiconductor production capacity to remain below demand through at least 2028.
Some have already expressed interest in placing equipment orders for 2029 and even 2030.
ASML previously outlined plans for approximately 30% more low-NA EUV and DUV immersion production capacity in 2027, while investigating a further 30% increase in 2028.
Management now believes those planned increases may still be insufficient to meet customer demand.
The company is therefore exploring additional capacity expansion for 2028 and beyond.
ASML expects to ship approximately 65 EUV systems in 2026, representing growth of more than 50% from the previous year.
This creates both an opportunity and a constraint: stronger long-term customer demand supports future revenue potential, but manufacturing capacity may limit how quickly ASML can deliver additional equipment.
Interest in equipment for 2029 or 2030 should not be treated as confirmed orders or guaranteed future sales.
How Can ASML Increase Chipmaking Capacity Without More Machines?
ASML is also helping chipmakers increase the productivity of existing manufacturing equipment.
The company plans to introduce the NXE:3800F in limited quantities in 2027, with throughput expected to increase from approximately 230 to 260 wafers per hour.
ASML also expects upgraded immersion systems to achieve approximately 330 wafers per hour.
Higher throughput allows manufacturers to process more wafers without requiring a proportional increase in factory space or equipment installations.
This explains why Installed Base Management is becoming increasingly relevant to ASML's revenue and margin outlook.
It also helps explain why customers may continue investing in upgrades even while placing orders for additional machines.
ASML Trading on MEXC: What Did the Futures Data Show?
ASML shares are listed on Nasdaq, but traders can also monitor semiconductor earnings exposure outside regular U.S. equity trading hours through MEXC stock derivatives.
ASMLUSDT Contract Metric | Snapshot |
Displayed contract price | 1,671.74 USDT |
Displayed change | −1.73% |
24-hour high | 1,747.04 USDT |
24-hour low | 1,642.35 USDT |
Index price | 1,670.31 |
Fair price | 1,671.03 |
Funding rate | 0.000095 |
The screenshot also displayed an approximately 76% bid-side versus 24% ask-side split within its order-book indicator.
That figure describes displayed order-book liquidity under the platform's calculation. It does not establish that 76% of traders held long positions, nor does it reveal the proportion of short sellers.
Likewise, a positive funding rate is not proof of widespread short covering or institutional buying.
The 24-hour trading range indicates significant price movement during the period covered by the snapshot, but the displayed change cannot by itself establish ASML's Nasdaq share-price reaction to the earnings announcement.
ASML Stock Futures vs. Real U.S. Stocks on MEXC
The ASMLUSDT perpetual contract is a derivatives product. It does not represent direct ownership of Nasdaq-listed ASML shares.
By contrast,
Real U.S. Stocks on MEXC provides access to U.S. equities through its brokerage-supported stock offering, subject to product availability and eligibility.
MEXC also distinguishes tokenized stocks from both traditional equity ownership and stock futures.
Investors should therefore distinguish among the products rather than treating their prices, trading hours and ownership rights as interchangeable.
In particular, an overnight perpetual contract quote should not be presented as ASML's official Nasdaq share price.
What Do ASML's Results Mean for TSMC, NVIDIA and Other AI Stocks?
ASML's Q3 results provide another indication that chip manufacturers are continuing to expand the infrastructure needed for AI computing.
TSMC (TSM): Demand for advanced manufacturing capacity supports investment in EUV lithography equipment. ASML's outlook adds context to TSMC's own capital spending and advanced-node expansion plans.
NVIDIA (NVDA): AI accelerator demand is an indirect driver of advanced semiconductor manufacturing investment, although ASML's equipment sales do not directly forecast NVIDIA's revenue.
AMD (AMD): Advanced processor demand contributes to long-term foundry capacity requirements and investment in manufacturing technology.
Micron (MU): AI workloads increase demand for advanced memory, potentially supporting equipment purchases and technology upgrades by memory manufacturers.
ASML also discussed progress in high-NA EUV technology, including adoption plans involving TSMC, Samsung and Intel.
These developments reinforce the importance of lithography equipment across the semiconductor industry, but the resulting financial contribution will depend on customer adoption schedules.
What Should Investors Watch After ASML's Q3 Earnings?
Three factors will determine whether ASML's earnings momentum can continue.
Equipment orders and backlog conversion. Strong customer interest is encouraging, but confirmed orders, deliveries and recognized sales remain distinct measures.
Capacity expansion. ASML believes its planned production increases may fall short of demand. Its ability to execute further expansion will influence future equipment deliveries.
Installed-base upgrades and pricing. Strong service and upgrade revenue supported Q3 margins, while higher value-based pricing could provide additional benefits from 2027 onward.
ASML's Q3 results establish a stronger fundamental picture through record revenue, improved margins and higher guidance.
Nevertheless, near-term share-price performance depends on market expectations, valuation and trading conditions. The MEXC overnight snapshot offers a separate view of derivatives activity, not a substitute for confirmed Nasdaq trading data.
FAQ
What were ASML's Q3 2026 earnings results?
ASML reported €11.662 billion in revenue, a 57.5% gross margin, €4.960 billion in net income and basic EPS of €12.95.
Did ASML raise its 2026 guidance?
Yes. ASML increased the lower end of its full-year revenue forecast from €43 billion to €44 billion, maintaining the upper end at €45 billion.
Why was ASML's gross margin above guidance?
Management cited stronger Installed Base Management revenue, productivity upgrades, favorable product mix and higher sales volume.
Why is ASML expanding production capacity?
Chipmakers are increasing equipment demand forecasts amid AI-related investment. ASML believes its currently planned capacity expansion may not fully satisfy demand in 2027 and 2028.